All Categories
Featured

Essential Strategies on 2026 Medicare Part D Enrollment
That versatility can be huge if your earnings modifications from year to year, or you go through a huge life event (such as divorce or short-lived work leave) and still desire to keep your policy in force. However it also means you'll require to pay closer attention to your policy over time.

This table highlights the most significant differences: Both entire life insurance and indexed universal life provide you with permanent coverage that builds money worth, but how that cash worth grows is rather various. Whole life insurance coverage generally has guaranteed development at a fixed rate, while IUL has the capacity for higher returns due to the fact that its money worth is tied to a market index.
Term life insurance is usually the most cost effective and most convenient kind of life insurance coverage to get. It doesn't build cash value, but you get a guaranteed death benefit for a set time period, often at a fraction of the cost of an IUL policy. You can consider a variable universal life insurance policy as one action above an IUL policy in terms of threat and reward.
This indicates you'll have greater growth capacity but likewise the possibility of financial investment losses. Like any financial product, indexed universal life insurance coverage has advantages and trade-offs. If your main goal is just replacing your earnings for your household, a term life insurance policy is typically simpler and far more economical.
Cheap Family Health Insurance in 2026
Common costs might include:, which generally increases as you age for managing the policy deducted from your payments if you include features like long-lasting care or chronic health problem advantages if you cancel the policy throughout its early years Before you buy an indexed universal life policy, the insurer will usually provide an illustration demonstrating how your policy could carry out over time.

Latest Posts

Top Medicare Supplement Plan Selection Tips
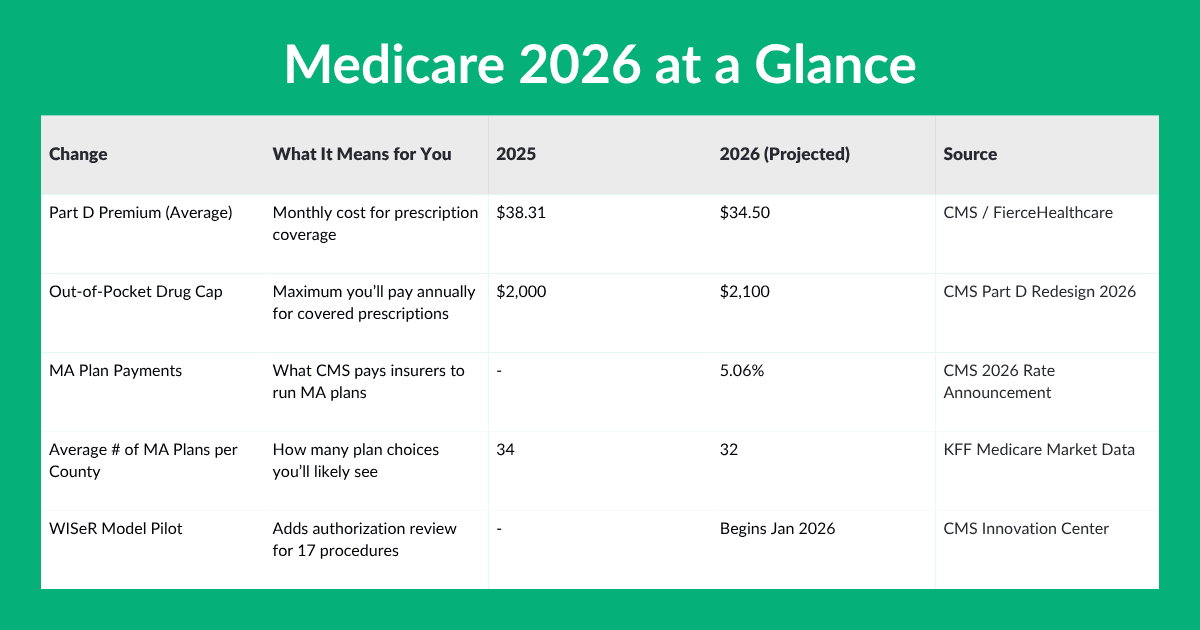
Direct Consumer Advice for Selecting 2026 Insurance
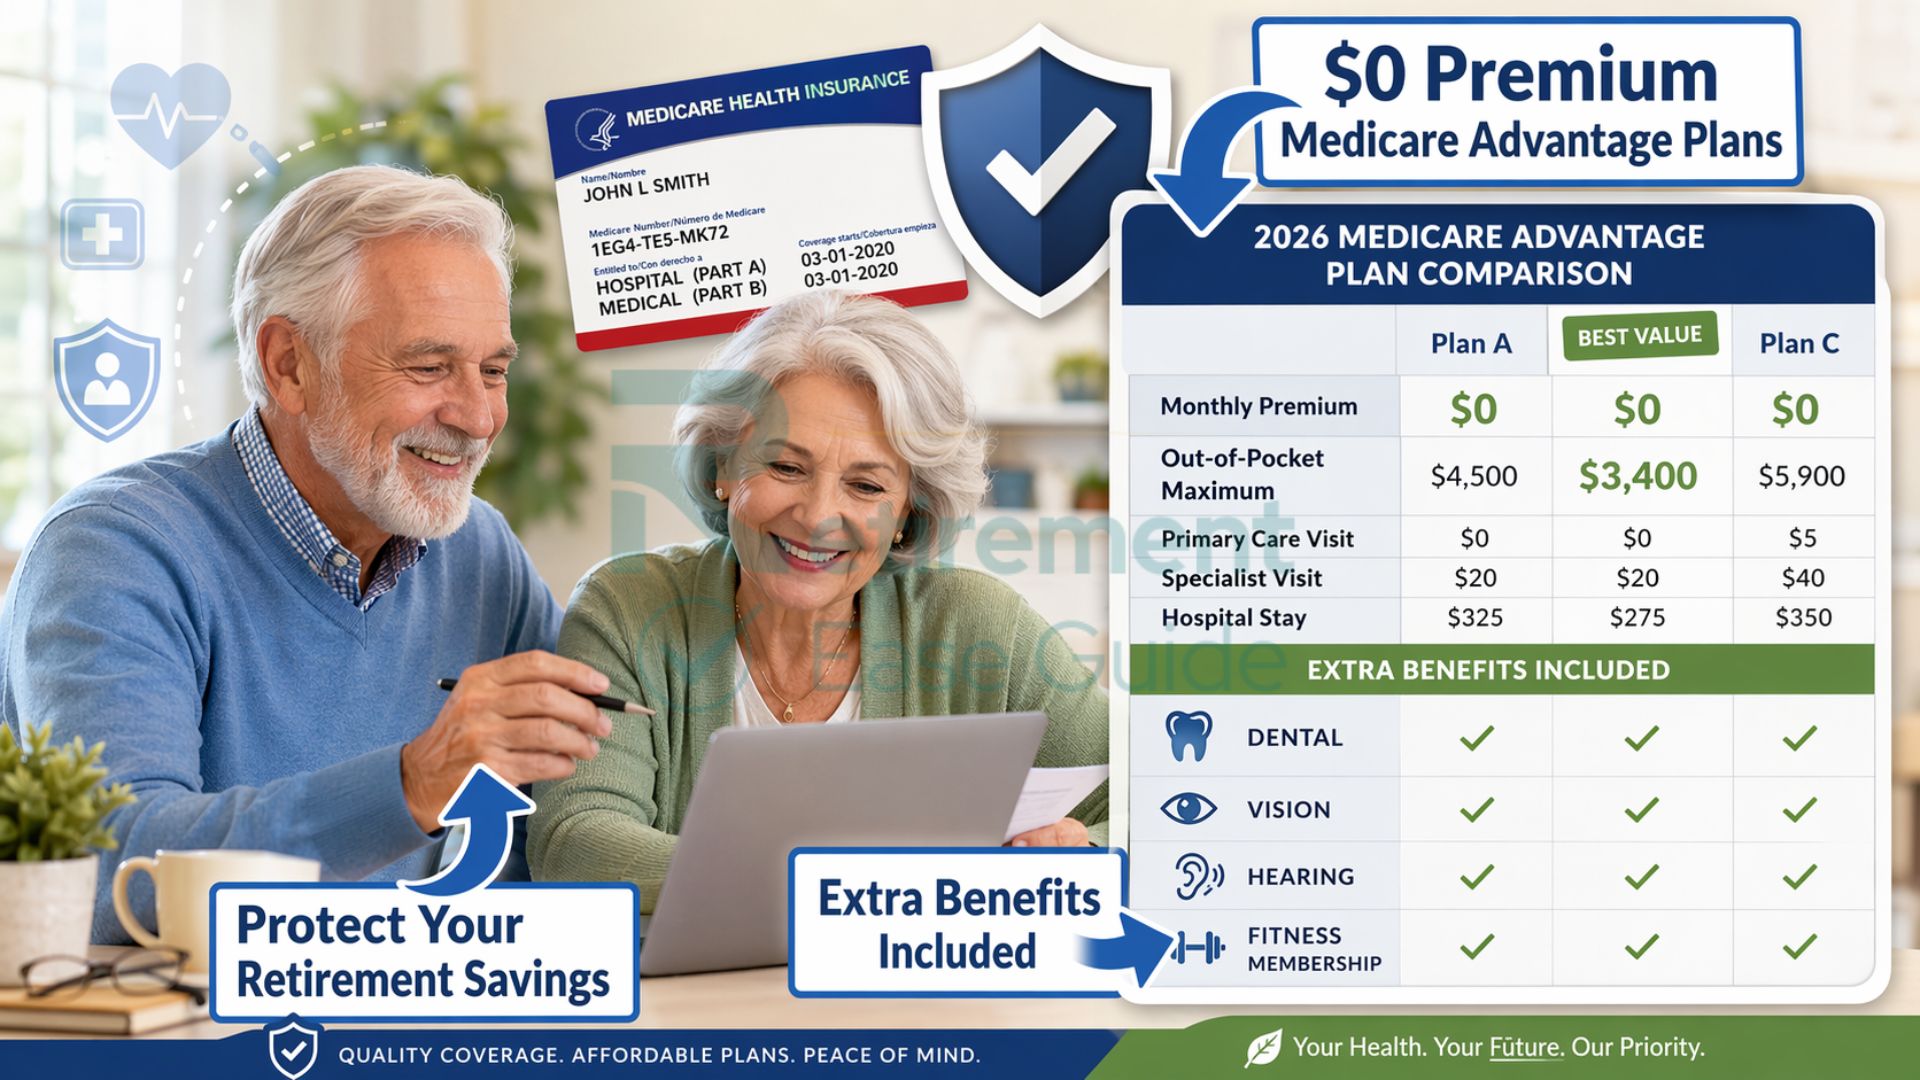
Life Insurance Rates for Veterans in the USA